Payroll Mistakes That Can Create Tax-Time Headaches

You know those little payroll details that seem harmless in the moment? The address that didn’t get updated. The W-4 that hasn’t been looked at in years. The bank account change mentioned after payroll has already been processed.

They may not seem like a big deal at the time, until tax season arrives, a paycheck gets delayed, or an employee gets an unexpected surprise.

A few of the most common payroll issues we see are also some of the easiest to prevent with timely communication and a quick review of employee information.

Federal withholding that does not match the employee’s situation

If an employee finds that too little federal tax has been withheld from their paycheck, the issue often traces back to their Form W-4. Life changes such as a new job, marriage, divorce, a second household income, dependents, or other income changes can all affect withholding.

Employers should not advise employees on how to complete their W-4, but they can point them to the IRS Tax Withholding Estimator. The IRS recommends checking withholding each January and after major life changes to help avoid an unexpected tax bill or penalty.

Incorrect employee address information

An outdated or incorrect address can create W-2 problems and, in Pennsylvania, may also lead to incorrect local withholding. Pennsylvania’s Department of Community & Economic Development notes that employees are required to complete a Residency Certification Form when hired and with any subsequent address change.

When an employee moves, they should complete a new Local Earned Income Tax Residency Certification Form so the employer has the correct PSD code and Earned Income Tax rate on file.

Employees find their local withholding rate and PSD code through Pennsylvania’s official Municipal Statistics address search tool.

Direct deposit changes were made too late

Another common payroll issue happens when an employee changes bank accounts and does not update their direct deposit information. If payroll is already being processed, a last-minute update may not be enough time to prevent a rejected deposit or payment delay. We can arrange to have a paper check issued during the account changeover so employees don’t miss a paycheck.

A good rule of thumb: employees should notify their employer of direct deposit changes before the end of the pay period, not on payday.

A little prevention goes a long way

Payroll accuracy depends on timely, accurate information. Encouraging employees to review their withholding, update address changes promptly, and communicate banking changes early can help reduce avoidable problems later.

For employers, clear reminders throughout the year can make a real difference. For employees, a few minutes of review now can prevent a much bigger headache at tax time.

Questions? We can help

Our experienced Payroll team is here to help you keep your payroll processes running smoothly. The links mentioned above, along with additional helpful information, can be found on our website as well.
Disclaimer

Any professional and technical information presented on this site is for interest only AND IS NOT INTENDED AS PROFESSIONAL ADVICE. It should not be relied upon without supporting professional advice on the subject in question. Neither the firm nor any member or employee of the firm will be responsible for any errors or omissions in the contents of this site howsoever caused.

This site contains links to other Web sites. We advise all web visitors to review the privacy and security policies of all externally linked sites before providing them with personal information. Canon Capital Management Group, LLC assumes no responsibility for the misuse of information volunteered to these sites.

New USPS Postmark Changes: What They Mean for Your Tax Filing Deadline

As the April 15 tax filing deadline approaches, we want to bring to your attention a critical change in United States Postal Service (USPS) procedures that affects how postmark dates are applied. This change is vital for anyone mailing tax returns, payments, or other time-sensitive documents.

What Has Changed?

The USPS has revised its postmarking process. Previously, mail was often postmarked with the date it was deposited at a local post office or in a mailbox. Under the new system, the postmark date will generally reflect the date the mail is first processed at a regional USPS sorting facility.

This means the postmark on your envelope could be one or more days after the date you mailed it.

Why This Is Critical for Your Tax Filings

Federal and state tax authorities rely on the postmark date to determine if a tax return or payment is filed on time. The long-standing “timely mailed, timely filed” rule depends entirely on the postmark.

With this new USPS procedure, a return or payment that you mail on or just before the tax deadline could receive a postmark dated after the due date. This would cause your filing to be considered late, potentially resulting in late-filing penalties, late-payment penalties, and interest charges.

Recommendations for a Timely and Secure Filing

To protect you from the risks associated with these new mailing procedures, we strongly advise the following:

  • Use Electronic Filing and Payment: The most secure and reliable way to file your taxes and pay any balance due is electronically. E-filing and electronic payments provide an official, dated confirmation of submission, eliminating any uncertainty related to mail delivery and postmarks. We encourage using this method whenever possible.
  • If You Must Mail Documents: If mailing is your only option, you can no longer rely on dropping your envelope into a standard mailbox to ensure a timely postmark. To obtain proof of timely mailing, you must take your documents to a post office retail counter and use one of the following services:
  • Certified Mail or Registered Mail: These services provide a mailing receipt postmarked by a postal employee and serve as official proof of the mailing date.
  • Request a Hand-Stamped Postmark: When mailing at the post office counter, you can ask the clerk to hand-cancel your envelope with a postmark showing that day’s date.
  • Use an IRS-Approved Private Delivery Service: Certain services from private carriers like UPS and FedEx are designated by the IRS as valid alternatives to USPS for timely filing.

 Please do not assume that dropping your tax documents in a USPS collection box on the due date will be sufficient to avoid penalties.

Have questions? Contact us online or call 215-723-4881.

Laura Eisenschmied

Bookkeeper/Administrative Support

Laura is a certified QBO Pro Advisor who joined Canon Capital in November 2021 following her time with Yzzi & Co. She provides administrative support to the firm and is an integral asset to our tax season process. Laura also performs bookkeeping services for our clients. A graduate of Upper Perkiomen High School, Laura lives in Souderton with her husband, Mark. They love spending time with their children and five grandchildren. In addition to spending time with family, Laura unwinds by working in her perennial garden; baking; biking; and travelling the USA, making stops in quaint towns along the way.

When to Bring Your CPA Into Big Financial Decisions

Running a business often means making decisions quickly. In the moment, the focus is usually on moving forward, keeping things running, and making the best call with the information you have. Only later does the full financial picture come into sharper focus.

It’s something we see from time to time. And it’s also where a quick conversation with your CPA can make things easier, especially before a decision is finalized rather than after it’s already in motion.

From replacing equipment to pursuing a new opportunity or hiring staff, consulting your CPA on these major spending and structural choices will help you see the full financial picture and make the right decisions.

Timing Matters

Most financial decisions in a business aren’t strictly “right” or “wrong.” What tends to matter more is how they’re structured, when they happen, and how they’re documented.

A purchase made in December can have a very different tax impact than the same purchase made in January. Hiring an employee instead of working with a contractor changes payroll obligations. Even the timing of income can affect estimated tax payments and cash flow.

These details aren’t always obvious at the moment, especially when you’re focused on the day-to-day running of the business.

It’s situations like these where a discussion with your CPA sooner rather than later is worth taking the time:

Scheduling Equipment or Large Purchases

Large purchases are one of the areas where timing tends to get overlooked.

In many cases, the decision is driven by need: a new truck, upgraded equipment, or a software system that will save time. The purchase makes sense operationally, so it moves forward.

But from a tax standpoint, timing and classification can matter more than most people expect.

Depending on the situation, a purchase may be:

  • Expensed immediately
  • Depreciated over time
  • Eligible for bonus depreciation or Section 179

Each option affects taxable income differently.

We’ve seen situations where moving a purchase forward by a few weeks or holding off until the new year, changed the outcome more than expected. It’s not always dramatic, but in some cases it’s more meaningful than expected.

Considering a Business Structure Change

As a business grows, the structure that worked early on doesn’t always remain the best fit.

This usually comes up when a business starts generating consistent profit. At that point, questions around entity type, owner compensation, and overall tax approach tend to follow.

For example:

  • Should you remain a sole proprietor or partnership?
  • Does an S-corporation election make sense at this stage?
  • How should owner income be handled going forward?

These decisions don’t just affect taxes. They can also impact quarterly payroll taxes, W-2 vs. K-1 reporting, and bookkeeping needs. When they’re thought through in advance instead of being handled quickly at year-end, the process is that much smoother.

Hiring Your First Employee (or Expanding Your Team)

Hiring is an exciting step, but it’s also where things can get complex quickly. Moving from independent contractors to employees introduces additional layers, like:

  • Payroll taxes
  • Withholding requirements
  • Unemployment insurance
  • Workers’ compensation
  • Reporting obligations

We’ve seen businesses hire first and then circle back to sort out the details. It’s understandable since hiring can happen quickly when help is needed but it can also create extra work later if details are sorted out afterward.

Many businesses hire quickly to meet immediate needs but later face extra compliance work. Talk to your CPA and your payroll provider before hiring to clarify costs and set-up.

Planning for Growth and Tax Strategy

Growth is a good problem to have, but it can create pressure if planning doesn’t keep up with it.

As revenue increases, so do estimated tax payments, exposure to additional state or local taxes, and reporting complexity.

We sometimes hear, “We had a great year, but the tax bill caught us off guard.”

Growth can push you into new filing requirements or higher estimated payments. Run projections with your CPA ahead of time if a decision could affect cash flow, taxes, or business structure to set expectations and avoid surprises.

Planning First Is Easier Than Fixing Later

That doesn’t mean slowing things down. These conversations are straightforward and focused while providing context that’s difficult to recreate after the fact.

There’s more flexibility when you have the conversation beforehand:

  • Adjust the timing
  • Refine the structure
  • Document from the beginning

Your CPA can still help after a decision, but options are narrower.

Need a Second Set of Eyes on a Big Decision?

The CPA team at Canon Capital Management Group works with business owners throughout Pennsylvania to align financial decisions with tax strategy, cash flow, and long-term goals.

In many cases, a quick check-in is enough to avoid complications later.

Have questions? We’re happy to talk. Contact us online or call 215-723-4881.

Privacy Statement

CPA’s, like all providers of personal financial services, are now required by law to inform their clients of their policies regarding privacy of client information. CPAs have been and continue to be bound by professional standards of confidentiality that are even more stringent than those required by law. Therefore, we have always protected your right to privacy.

Types of Nonpublic Personal Information We Collect
We collect nonpublic personal information about you that is provided to us by you or obtained by us with your authorization.

Parties to Whom We Disclose Information
For current and former clients, we do not disclose any nonpublic personal information obtained in the course of our practice except as required or permitted by law. Permitted disclosures include, for instance, providing information to our employees, and in limited situations, to unrelated third parties who need to know that information in order to assist us in providing services to you. In all such situations, we stress the confidential nature of information being shared.

Confidentiality and Security of Current and Former Clients’ Information
We retain records relating to professional services that we provide so that we are better able to assist you with your professional needs and, in some cases, to comply with professional guidelines. In order to guard your nonpublic personal information, we maintain physical, electronic and procedural safeguards that comply with our professional standards.

* * * * * * * *

We are committed to your financial well being, and protecting the privacy and security of the information you share with us is included in that commitment. You trust us with your personal and financial information, and we will continue honoring your trust by handling your information carefully and sensibly.

Casey Fixler

Level II Computer Technician

Casey Fixler joined Canon Capital in 2025, bringing with him more than two decades of in-depth experience in IT systems engineering, deployment, and leadership. Throughout his career, Casey has worked in a wide range of environments, designing and implementing secure, tailored technology solutions to meet the unique needs of his clients. His extensive background includes IT consulting, systems architecture, hardware diagnostics, software quality assurance, and network infrastructure management. A resident of Harleysville, Casey is passionate about technology and is always exploring new ways to solve problems and improve systems. Outside of work, he enjoys spending quality time with his family and staying on the cutting edge of the ever-evolving IT landscape.

Contact

Canon Capital Management Group
CPA, Payroll, Technologies

484 Harleysville Pike
PO Box 228
Harleysville, PA 19438

215.723.4881 phone
215.723.1487 fax

Our Location:

Avoiding Tax Surprises During Rapid Business Growth | CPA Guidance for Growing Companies

Growth is a good problem to have. When you’re winning new contracts, experiencing rising revenue, and growing a team, everything looks like it’s moving in the right direction. On paper, that is.

From a CPA’s perspective, however, rapid growth is one of the most common reasons Pennsylvania business owners are caught off guard by unexpected tax bills and cash-flow strain.

The issue isn’t growth itself. It’s how quickly the rules change when your numbers do.

Why Growth Can Tighten Cash Flow

One of the biggest misconceptions we see is simple: more revenue automatically means more available cash. In reality, fast growth often reduces short-term cash flexibility, even when profits increase.

Why?

Taxes scale quickly. As income rises, so do federal and Pennsylvania estimated tax payments. Payroll taxes grow with each new hire. Additional local earned income tax filings or Local Services Tax obligations may be triggered if your business expands into new municipalities. Without early planning, those changes often show up as a surprise notice or a much larger than expected tax payment.

Timing matters. Revenue is taxed when it’s earned, not when cash is collected. If receivables lag while payroll, rent, and vendor expenses rise, cash can feel tight during your most successful months.

Spending accelerates before strategy adjusts. Growth often requires quick decisions: hiring staff, purchasing equipment, upgrading technology, or outsourcing services. How those costs are treated for tax purposes (deducted, capitalized, or depreciated) has a direct impact on taxable income.

Your structure may no longer fit. An entity set-up or owner compensation strategy that worked at lower revenue levels may be inefficient as profits grow. Retirement contributions, pass-through income planning, and payroll strategy often need to be revisited sooner than expected.

None of this means something is wrong. It simply means your financial picture has changed and your tax strategy needs to change with it.

When Business Owners Usually Call Their CPA

Many business owners reach out only after growth has already happened, when:

  • A larger-than-expected tax bill arrives
  • Cash feels tighter despite strong sales
  • Estimated payments jump unexpectedly
  • A lender or investor asks for financial clarity

At that point, the CPA’s role becomes reactive instead of strategic. While issues can still be addressed, opportunities around timing deductions, payroll strategy, or estimated tax planning may already be limited.

 Call Your CPA Before You Commit

A short CPA conversation before a major growth decision can prevent months of stress later.

Early input matters most when:

  • A new contract significantly increases revenue: especially if payment timing changes
  • You’re hiring multiple employees or contractors: triggering higher payroll taxes, PA unemployment contributions, and affecting classification considerations
  • You expand into new municipalities or states: which can create new tax filing and compliance requirements
  • You’re purchasing major equipment or software: where tax treatment affects income more than expected
  • Growth follows several lean years: when prior losses or credits may still be leveraged with proper planning

A brief planning discussion at this stage often saves far more than it costs.

What CPA Growth Planning Actually Covers

 From the CPA side, planning isn’t about slowing growth. It’s about removing friction. That planning often includes:

  • Adjusting federal and Pennsylvania estimated tax payments
  • Forecasting cash flow with taxes included
  • Reviewing entity structure and owner compensation
  • Coordinating payroll, benefits, and retirement contributions
  • Identifying deductions and credits tied to expansion
  • Ensuring financial reporting aligns with lender or investor expectations

The goal is predictability, not perfection.

 Growth Is Easier When Taxes Aren’t A Surprise

Fast growth should feel exciting, not stressful. The businesses that navigate it most smoothly are the ones that involve their CPA early and treat tax planning as part of growth planning.

Growth changes your numbers. A proactive CPA helps make sure it doesn’t change your sleep.

Planning for Growth? Talk It Through

 If your business is growing quickly, or preparing to sign a major new contract, a short planning conversation can help clarify the tax and cash-flow implications before they become problems.

Our CPA team here at Canon Capital Management Group works with business owners to align tax strategy, cash flow, and growth decisions so success doesn’t come with surprises.

Have questions? We’re happy to talk. Contact us online or call 215-723-4881.

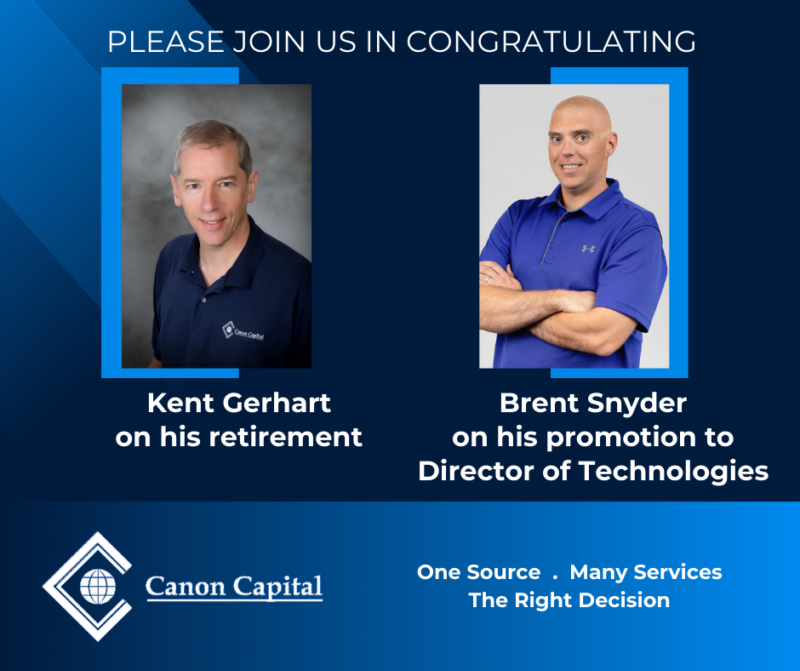
Canon Capital Technologies Announces Retirement of Kent Gerhart and Promotion of Brent Snyder to Director of Technologies

Kent Gerhart has retired from his role as Director of Technologies after more than 35 years in the technology field and over two decades with Canon Capital Management Group. Since joining us in November 2000, Kent has been a steady presence behind the growth of our technology division, helping clients adapt as systems, security, and infrastructure evolved over the years. His career spans roles as a programmer, analyst, and consultant, as well as ownership of KenTech Information Systems, Inc., an experience that shaped his practical, client-first approach.

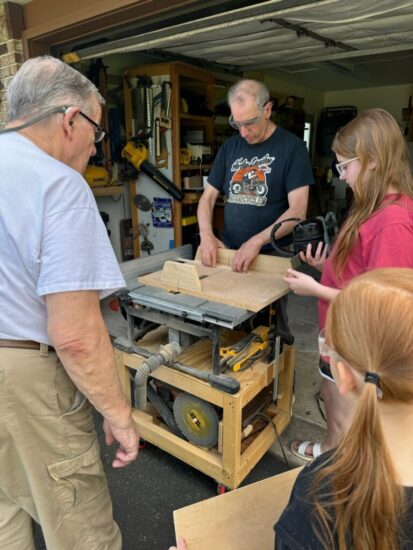
Kent Gerhart woodworkingAs he enters retirement, Kent is looking forward to a new and meaningful role as a part-time caretaker for his first grandchild while continuing to work part-time in his custom woodworking business.

Brent Snyder has been named our new Director of Technologies. He joined Canon Capital Management Group in October 2024, bringing more than 25 years of experience in technology and operations. Brent holds a B.A. from Temple University and is a graduate of the Fox School of Business. Brent continues to demonstrate the strong leadership, operational expertise, and customer-focused approach that our clients have come to expect.

Brent is active in the local community, serving on the boards of Harleysville Baseball and #IronDad23, a nonprofit supporting families in the Souderton Area School District. He lives in Souderton with his wife, Laurie, and their two sons.

We thank Kent Gerhart for his lasting contributions and look forward to continued growth and innovation under Brent Snyder’s leadership.